

Square Point of Sale: Payment
by Block, Inc.
4.6
- Safety
- 100% Safe
- Category
- Business
- Ratings
- 4.6
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots

 Analysis by Getfullapps
Running a small business often means switching between selling, recording payments, checking orders, and keeping customer details organized. Square Point of Sale is built around reducing that switching. It turns a compatible mobile device into the working screen for a business, with tools aimed at sales, invoices, retail, restaurants, and appointments. After spending time with it, I found that its biggest strength is not simply accepting a payment; it is keeping the payment connected to the sale that created it.
That distinction matters. A basic card reader can take money, while a notebook can record what was sold, but managing both separately creates avoidable work. Square Point of Sale brings those tasks into one business-focused app from Block, Inc. It is free to install, suitable for Everyone, and available on devices running a recent enough operating system. Its current version is 7.17, and the app has been available since May 11, 2010, which gives it a long history in mobile point-of-sale software.
I would not describe it as a universal replacement for every accounting, inventory, or hospitality system. Instead, I see it as a practical central counter for small operations that want a clear way to turn a customer interaction into a recorded transaction. The experience is strongest when the owner or staff member needs to sell quickly without losing track of the details afterward.
Why the payment workflow is the real value
The payment screen is only the visible end of the process. Before reaching it, a seller may need to select products, adjust a quantity, apply the right sales details, and make sure the transaction is associated with the correct order. When that information stays together, the business has a more useful record than a simple notification saying that money arrived.
In my experience, this makes Square Point of Sale more useful than a standalone payment tool for shops and service providers that handle repeatable sales. A market stall may use it to ring up several items in one visit. A small café can use the same basic idea for a customer order. Someone offering appointments can benefit from having the commercial side of the visit handled in the same business environment rather than writing a payment note elsewhere.
The app’s category is Business, and that is an important expectation to set. It is not trying to entertain the customer or act like a personal wallet. The interface and workflow are designed around the person taking the sale. That means the best results come when the owner takes a little time to arrange the selling process before a busy period begins.
The practical advantage is continuity: the sale, the amount, and the payment action belong to one workflow instead of becoming separate chores. That can reduce small mistakes that are easy to make when a seller accepts money in one place and records the transaction later from memory.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What a normal sale feels like
A typical interaction starts with the seller building the transaction rather than immediately asking how the customer will pay. For a product-based business, that means choosing the items involved. For a service business, it may mean connecting the charge to the appointment or service being delivered. Once the total is ready, the payment step becomes the natural conclusion of the order.
This order of operations sounds obvious, but it changes the pace of work. I prefer it to a loose payment-first approach because the customer’s purchase is defined before the final amount is accepted. If a customer changes their mind, the seller can adjust the transaction before completing it instead of trying to repair a vague payment record later.
It also helps during handoffs. If one person begins an order and another person finishes it, a structured point-of-sale screen gives the second person something concrete to review. That is more dependable than relying on a verbal explanation such as “they had two items and paid about this much.” For a small team, this kind of clarity can be more valuable than a long list of advanced options.
The app works best when the business keeps its catalog or service choices tidy. A cluttered selection screen slows down the very workflow the app is meant to simplify. I would spend time removing outdated entries, using names that staff understand immediately, and grouping products in a way that matches the physical layout of the shop or the order in which services are normally delivered.
Using it when the day gets busy
The difference between a good point-of-sale app and an irritating one usually appears during a rush. When several customers are waiting, the seller needs to find the right item quickly, confirm the total without hesitation, and move to the next customer without losing the previous transaction.
Square Point of Sale is well suited to that rhythm when the business has predictable products or services. It gives the seller a dedicated transaction flow instead of forcing them to improvise with a generic payment app. The screen becomes a checklist: identify the sale, confirm it, complete the payment, and leave a usable record.
My advice is to rehearse the complete path before relying on it at a busy event. Do not only test opening the app or viewing the catalog. Practice correcting a quantity, handling a customer who changes an item, and moving from the order screen to payment. These are the moments where hesitation appears, and preparation is more useful than assuming the interface will be self-explanatory under pressure.
Another useful habit is separating setup time from selling time. Product names, service choices, and staff routines should be settled before customers arrive. The app can support the transaction, but it cannot decide how your business should organize its menu or workflow. Owners who treat configuration as part of operations will get more from it than those who install it five minutes before opening.
A realistic example: a weekend seller
Imagine I am selling handmade goods at a weekend market. I have a small range of products, customers who ask for several items at once, and limited space behind the table. With Square Point of Sale, I can build the customer’s order on the device, review the total, and complete the payment without writing each item on paper first.
The benefit is not merely speed. At the end of the event, I have a more meaningful view of what was sold than I would have if I had accepted payments with a general-purpose wallet and made rough notes in a notebook. If a particular product sells more often than expected, that information can influence what I bring to the next market.
There is a trade-off in this example. The seller must keep the product list accurate and make sure the device is ready for the environment. A crowded market, bright sunlight, limited connectivity, or a long queue can expose weaknesses in preparation. The app makes the transaction process more organized, but it does not remove the operational demands of selling outdoors.
This is also where I would avoid overpromising. A seller with only occasional transactions may find a simple payment method easier, especially if they do not need item-level records. Square Point of Sale earns its place when the business benefits from connecting the payment to the sale, not merely from having another way to accept money.
Where it fits for restaurants and appointments
The same payment-centered idea changes slightly in a restaurant. The important question is not only whether the customer can pay, but whether the payment belongs to the correct order. Staff need to know what was ordered, what remains open, and which transaction is being completed. A point-of-sale workflow is more appropriate for that environment than a generic transfer tool.
For appointments, the value is different again. A service provider may care less about a product catalog and more about making sure the charge follows the client’s visit. The app’s support for appointments makes it relevant to businesses where the sale is tied to time and service rather than a physical item. I would still keep the workflow simple: define the service clearly, confirm the amount before payment, and avoid forcing staff to search through a confusing list.
These examples show why I would not judge the app only by how quickly it opens a payment screen. The stronger question is whether the business needs a record of the commercial context around that payment. If it does, the point-of-sale approach makes sense. If it does not, the extra structure may feel unnecessary.
Invoices and sales beyond the counter
A counter is not the only place where a business gets paid. Some customers need an invoice, while others buy directly from a retail display or service desk. The inclusion of invoices broadens the app’s usefulness because the business is not forced into a single face-to-face checkout pattern.
I see this as especially helpful for a small operator who does several kinds of work but does not want to maintain completely separate systems. A seller might handle an immediate retail purchase one day and send an invoice for a larger job another day. Keeping those activities within the same business-oriented app can make the overall routine easier to understand.
There is a limit, though. A payment app should not automatically be treated as a full accounting package. Businesses with complicated bookkeeping, extensive reporting needs, or specialized industry rules may eventually need dedicated software alongside it. Square Point of Sale can be a useful operational layer, but I would not make it the only tool for every financial responsibility without checking that it matches the business’s requirements.
The trade-offs I noticed before recommending it
The first trade-off is simplicity versus structure. The app is more organized than a basic payment method, but that organization requires setup and consistent use. If staff skip the item selection and treat the device as a quick money-collection screen, the business loses much of the benefit. In other words, the app rewards disciplined workflows rather than casual use.
The second is dependence on the device and the surrounding payment setup. A mobile point of sale is convenient because it travels with the business, but that also means the device must be ready when customers are ready. I would check the device beforehand, keep the app updated, and make sure staff know what to do if the normal checkout routine is interrupted.
The third trade-off concerns scale. A small shop, independent service provider, or occasional seller may appreciate the focused workflow. A larger operation with highly specialized inventory, complex staff permissions, or deep industry reporting may prefer a more comprehensive retail or restaurant platform. Square Point of Sale can be a strong starting point, but “mobile” does not automatically mean “suitable for every size of business.”
Another consideration is staff training. The basic sale may be easy to understand, but real operations include corrections, unusual orders, invoices, and customer questions. I would create a short internal routine for staff: verify the items, confirm the total aloud, complete the payment, and check that the transaction is finished before serving the next customer. This small discipline prevents the app from becoming a source of uncertainty during a rush.
The app’s age rating of Everyone makes it broadly approachable from a content perspective, but that does not mean every business process is automatically simple. The person using it still needs to understand the business’s prices, services, and policies. The software can present the transaction; it cannot replace good operational decisions.
How it compares with familiar alternatives
Compared with cash and a paper ledger, Square Point of Sale offers a more connected way to record a sale and move through payment. Cash can be perfectly adequate for a small operation, but it creates counting, change, and end-of-day reconciliation tasks. Paper records are flexible, yet they depend heavily on careful handwriting and memory.
Compared with a general digital wallet, the app is more business-specific. A wallet may be faster for sending or receiving money, but it usually does not provide the same sense of a product or service being checked out. For a business that wants item-level context, an actual point-of-sale workflow is the better fit.
Compared with a full retail suite, Square Point of Sale is easier to approach but may not cover every advanced operational need. A larger system can be worthwhile for a multi-location business or a company with complicated stock control and reporting. I would choose Square when the priority is a manageable mobile checkout connected to everyday selling, not when the priority is building an elaborate enterprise back office.
This is why I would not call it simply “the best” payment app. It is better for a particular kind of decision: choosing whether a business needs a straightforward mobile point of sale rather than a bare payment button or a heavyweight management system.
Who will get the most from it
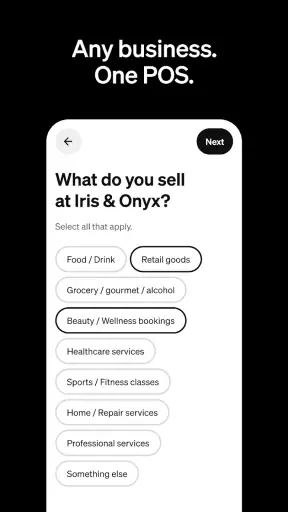
I think Square Point of Sale is a strong match for independent retailers, food sellers, appointment-based professionals, and small teams that want sales and payments to live in one workflow. It is also appealing to owners who move between locations and do not want their checkout tied to a traditional fixed counter.
The free price makes it easy to try without treating installation as a major financial commitment. The app has passed the ten-million-install mark and holds a 4.6 average from roughly two hundred fifty-nine thousand ratings, with about fifty-four thousand written reviews. Those figures suggest that it has reached a broad audience, although popularity alone should not decide whether its workflow suits a particular business.
I would recommend testing it with the most common sale first. Add the products or services staff use every day, run a complete transaction, and then try the same process with a correction or an invoice. If those steps feel natural, the app is likely to reduce friction. If the setup already feels too detailed for the business, a simpler payment option may be more sensible.
I would also skip it as the primary system if the business needs deep industry-specific controls that a mobile point of sale cannot reasonably provide. A complex restaurant group, a large inventory operation, or a company with demanding accounting procedures should compare it with specialized systems rather than assuming a popular mobile app will cover everything.
My final take after using the workflow
Square Point of Sale succeeds because it treats payment as the final part of a sale instead of the entire sale. That sounds like a small distinction, but it affects how clearly a business can work during the day and review its activity afterward. I found the app most convincing when I imagined repeated transactions, changing customer orders, and staff needing a shared routine.
Its weaknesses are the natural cost of that approach: setup matters, device readiness matters, and businesses with advanced requirements may outgrow it. Still, for a small operation that wants a mobile checkout with more context than a basic transfer tool, the balance is attractive.
Block, Inc. has positioned the app for practical business use, and I think that description fits. It is free, focused, and broad enough to cover retail, restaurants, invoices, and appointments without pretending that every business has the same needs. If your main goal is to turn everyday customer interactions into organized, completed sales, this is an app I would genuinely suggest trying.
Pros
- Easy setup for quick transactions.
- Compatible with various payment methods.
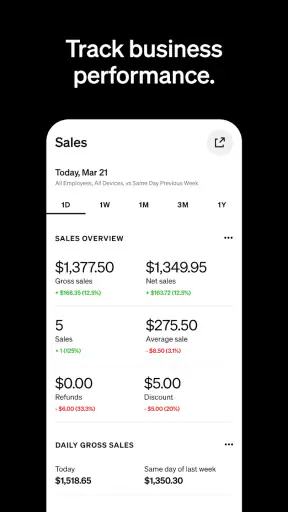
- Real-time sales analytics provided.
- User-friendly interface for all.
- Secure transactions with encryption.
Cons
- Limited offline functionality.
- Fees for card processing.
- Occasional app freezes reported.
- Requires stable internet connection.
- Some features need subscription.
FAQs for Square Point of Sale: Payment
What types of payments can I accept with Square Point of Sale?
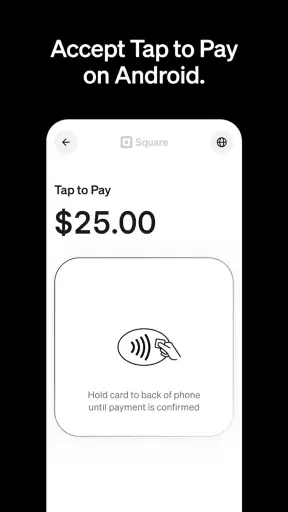
Square Point of Sale allows you to accept a wide range of payment methods, including credit and debit cards, contactless payments like Apple Pay and Google Pay, and even gift cards. This versatility ensures that you can cater to various customer preferences, making transactions smooth and efficient.
Is Square Point of Sale secure for handling transactions?
Yes, Square Point of Sale is designed with security in mind. It uses end-to-end encryption to protect transaction data and adheres to PCI compliance standards. Regular updates and security measures ensure that both your business and customer information remain safe from potential threats.
What kind of hardware is compatible with Square Point of Sale?
Square Point of Sale is compatible with various hardware options, including Square Reader for magstripe, Square Stand for iPad, and the Square Terminal. These devices are designed to integrate seamlessly, providing a flexible and scalable solution for businesses of all sizes.
Are there any fees associated with using Square Point of Sale?
Square Point of Sale does not have monthly or startup fees, but it does charge a transaction fee for each payment processed. This fee varies depending on the type of transaction but is typically a percentage of the total sale. It's essential to review these fees to understand the cost implications for your business.
Can I manage inventory and view sales reports with Square Point of Sale?
Yes, Square Point of Sale offers robust inventory management and reporting features. You can track stock levels, receive low-stock alerts, and generate detailed sales reports. These tools help you make informed business decisions and streamline your daily operations, enhancing overall efficiency.

Square Point of Sale: Payment
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via square@help-messaging.squareup.com, visit https://square.com/help, or review their https://squareup.com/legal/privacy.










